UAE Interest Rate Hike 2026: What It Means for Dubai Property Buyers
The US Federal Reserve raised its target interest rate by a quarter point to 3.75-4.00% on 16 September 2026, a 12-0 vote. The Central Bank of the UAE (CBUAE) announced the same day that it was lifting its Base Rate from 3.65% to 3.90%, effective Thursday 17 September 2026, as reported by Gulf News on 16 September 2026. The 3-month EIBOR (Emirates Interbank Offered Rate, the daily benchmark UAE banks use to price variable-rate loans, published by the CBUAE) stood at 4.13% on 16 September and 4.36% on 18 September, per the CBUAE's own EIBOR page, updated 18 September 2026. As recently as April, the Fed's own statement still leaned toward cuts. This is a rise, and what it changes depends on how you are financing your Dubai property purchase.
Methodology: Every figure below is taken from the US Federal Reserve's own press releases, the Central Bank of the UAE's own EIBOR page and Rulebook, and named Tier-1 UAE press (Gulf News, Khaleej Times). Rate figures are dated 16-20 September 2026; the CBUAE lending rules cited date from 2013 and the one mortgage-rate reference is from June 2026, each labelled where it appears. Where a figure could not be confirmed against a named source, including the cash-versus-mortgage split of Dubai purchases and any bank's current mortgage rate, this article says so rather than estimating.
Key takeaways
✓ Fed raised its target range 25 basis points to 3.75-4.00% on 16 September 2026 (vote 12-0).
✓ CBUAE raised its Base Rate 3.65% → 3.90%, effective Thursday 17 September 2026 (Gulf News, 16 September 2026).
✓ 3-month EIBOR: 3.99% on 1 September, 4.18% on 15 September, 4.13% on 16 September, 4.36% on 18 September (Central Bank of the UAE, updated 18 September). It was already climbing before the decision, and it moves daily.
✓ Fixed-rate borrowers feel nothing today; variable-rate and end-of-fixed-period borrowers are exposed at their bank's next reset.
✓ CBUAE loan-to-value (LTV) caps have applied since 28 December 2013 (Circular 31/2013, Article 3). Not a new rule.
✓ Off-plan mortgages stay capped at 50% LTV regardless of buyer category; developer instalments involve no bank loan at all.
What did the US Federal Reserve actually decide on 16 September 2026?
The Federal Open Market Committee "decided to raise the target range for the federal funds rate by 1/4 percentage point to 3-3/4 to 4 percent," per the Fed's own press release dated 16 September 2026 (federalreserve.gov). The vote was unanimous, 12-0. The statement carried no forward guidance on future moves, so this article makes no prediction of what happens next either.
The Fed held its target range at 3.50-3.75% at its April, June and July 2026 meetings, so this was not a sudden reversal. At the 29 July meeting, the vote to hold was 9-3: three members, Hammack, Kashkari and Logan, "preferred to raise the target range for the federal funds rate by 1/4 percentage point at this meeting." Our reading: a hike had support inside the Committee two months before it happened. This had been building for a while.
How did the CBUAE respond, and what is EIBOR doing right now?
The CBUAE's Base Rate (the rate the Central Bank pays on the Overnight Deposit Facility, anchoring its own policy stance) is mechanically tied to the Fed's Interest Rate on Reserve Balances because of the dirham's peg to the US dollar. Gulf News reported on 16 September 2026 that the CBUAE raised its Base Rate by 25 basis points, from 3.65% to 3.90%, effective Thursday 17 September 2026, following the Fed's move on 16 September. We could not open the CBUAE's own press release page directly, so we attribute this to Gulf News's report rather than a CBUAE-owned page.
EIBOR is the benchmark UAE banks actually use to price loans, including mortgages. The CBUAE's own EIBOR page (centralbank.ae, updated Friday 18 September 2026) states plainly: "The EIBOR is also the reference rate used by borrowers and lenders to conduct financial transactions in the UAE for loans such as mortgages, personal and car loans." EIBOR changes daily, so any figure needs its date attached. The 3-month tenor was 3.99% on 1 September and 4.18% on 15 September, already climbing before the decision. Around the decision itself, it moved from 4.13% on 16 September to 4.36% on 18 September, roughly +0.23 of a point. Our reading: the overnight fixing, at 3.41% on 16 September, jumped to 3.65% on 17 September (the day the CBUAE's change took effect). That is the clearest evidence in the daily data that the Base Rate move landed.
| Date | 1-month EIBOR | 3-month EIBOR | 6-month EIBOR |
|---|---|---|---|
| 1 Sep 2026 | 3.76% | 3.99% | 4.06% |
| 15 Sep 2026 | 3.94% | 4.18% | 4.20% |
| 16 Sep 2026 (Fed decision day) | 3.99% | 4.13% | 4.20% |
| 17 Sep 2026 (CBUAE hike effective) | 4.00% | 4.21% | 4.25% |
| 18 Sep 2026 | 4.01% | 4.36% | 4.26% |
Source: Central Bank of the UAE, EIBOR rates page (centralbank.ae/en/forex-eibor/eibor-rates/), stamped "Last updated: Friday 18 September 2026". EIBOR is published daily and will have moved again by the time you read this. Check today's figure with your lender rather than relying on this table for a live rate.
Who feels a rate rise immediately, and who does not?
UAE mortgages are typically structured with a fixed rate for an initial period (commonly one, two, three or five years), after which the loan moves to a variable rate tied to 3-month EIBOR plus a fixed margin. HSBC UAE's own mortgage-rates page confirms this structure. Once a loan is in its fixed period, that rate does not change regardless of what the Fed or CBUAE do. The reset happens only when the fixed period ends.
Gulf News, reporting on 16 September 2026, made the point directly: "Thursday's increase does not mean every mortgage payment automatically rises overnight." Borrowers already on a variable rate, or whose fixed period is ending soon, are exposed. Exactly when depends on each bank's own review schedule, which is why asking your own lender directly is the practical first step. For context, Khaleej Times, 17 June 2026 (before the hike), reported that one mortgage provider was then quoting a one-year fixed rate of around 3.75%. That is a single pre-hike data point, not a market average, and it predates the September moves.
Buyers with a mortgage inside a fixed-rate period
Nothing changes on your monthly payment until your fixed period ends and the loan rolls onto EIBOR plus your bank's margin. Find out from your lender exactly when that reset date falls. It is bank- and loan-specific, not a single UAE-wide date.
Buyers on a variable rate, or approaching the end of a fixed period
This is the group Gulf News's 16 September coverage was speaking to directly. The next review point on your loan is where a higher EIBOR shows up. If you are weighing a new fixed period against staying variable, your own bank is the only source that can price both options for your loan. See our rent-vs-own payment plan comparison for a broader look at instalment structures.
Cash buyers
No mortgage means no direct effect from the Fed's move or the CBUAE's Base Rate change. No reset date, no EIBOR exposure. We are not citing a percentage for how much of the Dubai market is cash-funded: the figures we found conflicted, and none could be confirmed against a single named, dated source.
What are the CBUAE's loan-to-value and debt-burden rules, and are they new?
No. The rules below come from the Central Bank of the UAE Rulebook, Article (3), "Important Ratios," under Circular 31/2013, marked "Effective from 28/12/2013" and "Status: In-Force". These loan-to-value (LTV: the maximum percentage of a property's value a bank will lend against) caps have applied since December 2013; nothing here changed with this September 2026 rate move.
| Buyer category | Property value | Maximum LTV |
|---|---|---|
| UAE national, first home / owner-occupier | ≤ AED 5 million | 85% |
| UAE national, first home / owner-occupier | > AED 5 million | 75% |
| UAE national, second home or investment | Any value | 65% |
| Expatriate, first home / owner-occupier | < AED 5 million | 80% |
| Expatriate, first home / owner-occupier | > AED 5 million | 70% |
| Expatriate, second home or investment | Any value | 60% |
| Any buyer, off-plan property | Any value | 50% |
Source: Central Bank of the UAE Rulebook, Article (3) "Important Ratios," Circular 31/2013, effective 28 December 2013, status In-Force. Off-plan LTV is capped at 50% "regardless of purpose, value, or category of purchaser." Banks may lend below these maximums at their own discretion, so confirm the actual figure your lender offers.
The same Rulebook article sets a debt-burden ratio (DBR: the share of your gross monthly income that can go toward loan repayments) cap of 50% of gross salary and regular income, and requires lenders to "stress test the loan at (2 to 4) percentage points above the current rate of interest on the loan." Our reading: banks were already assessing affordability at a rate several points higher than today's actual rate before this hike. That is a cushion built in for exactly this kind of move. Maximum tenor is 25 years; maximum financing is capped at 8 years of annual income for UAE nationals, 7 for expatriates.
Want help working out which of these applies to you?
Whichever category you fall into, the right next step is confirming your own numbers with your lender before acting on general news. For a second opinion on a specific listing or payment structure, speak to us on WhatsApp or book a free 15-minute consultation.
What does this mean if you are buying off-plan on a developer instalment plan?
Developer instalment plans work differently from a bank mortgage. Instalments during construction are paid directly to the developer, with no bank loan involved at that stage, so a Fed or CBUAE rate move has no direct effect on those payments. What often follows, though, is a handover balance, which frequently needs a mortgage if the buyer is not paying cash. The rate on that eventual loan is whatever applies on the day it is drawn: higher, lower or unchanged from today, and not knowable now. If a mortgage is used, the same 50% off-plan LTV cap set out above still applies, regardless of how the instalments were structured beforehand.
For a fuller comparison against buying resale, see our off-plan vs resale comparison, and for risks worth understanding before signing, see what agents won't tell you about off-plan risk. For transaction volumes independent of this rate move, see our DLD transactions Q1 vs Q2 2026 breakdown.
What is not known yet?
Being direct about the gaps matters as much as the confirmed figures. As of 20 September 2026, four days after the Fed's decision, no named UAE bank, brokerage or consultancy has published commentary specifically reacting to this move's effect on Dubai property. The Fed's statement gave no guidance on its future rate path, so there is nothing to report on the next meeting. How quickly each bank reprices existing variable loans is bank-specific and unpublished in aggregate. A reliable, single, dated figure for the cash-versus-mortgage split of Dubai purchases could not be confirmed from the sources checked. Where figures conflicted, neither is used here.
Five questions to ask your bank before you act
✓ What is my loan's fixed-period end date, and what margin applies once it rolls to variable?
✓ What is today's 3-month EIBOR reading, and how does the bank apply it to my loan?
✓ If I lock in a new fixed period now, what rate is on offer, and for how long?
✓ For an off-plan purchase, what LTV and DBR assessment applies to my handover-balance mortgage?
✓ Does the bank's stress-testing buffer already cover a scenario like this one?
The one question we would not proceed without answering is the first: your own fixed-period end date. That figure is specific to your loan, and only your lender can confirm it.
What we are telling buyers at Early Bird
A financing decision depends on your timeline and the specific property, not on one rate move. We are not forecasting where rates go from here. We tell mortgage buyers to get their fixed-period end date and EIBOR-plus-margin terms in writing from their bank. We tell off-plan buyers to ask now, before signing, how their handover-balance mortgage would be assessed under today's LTV and DBR rules.
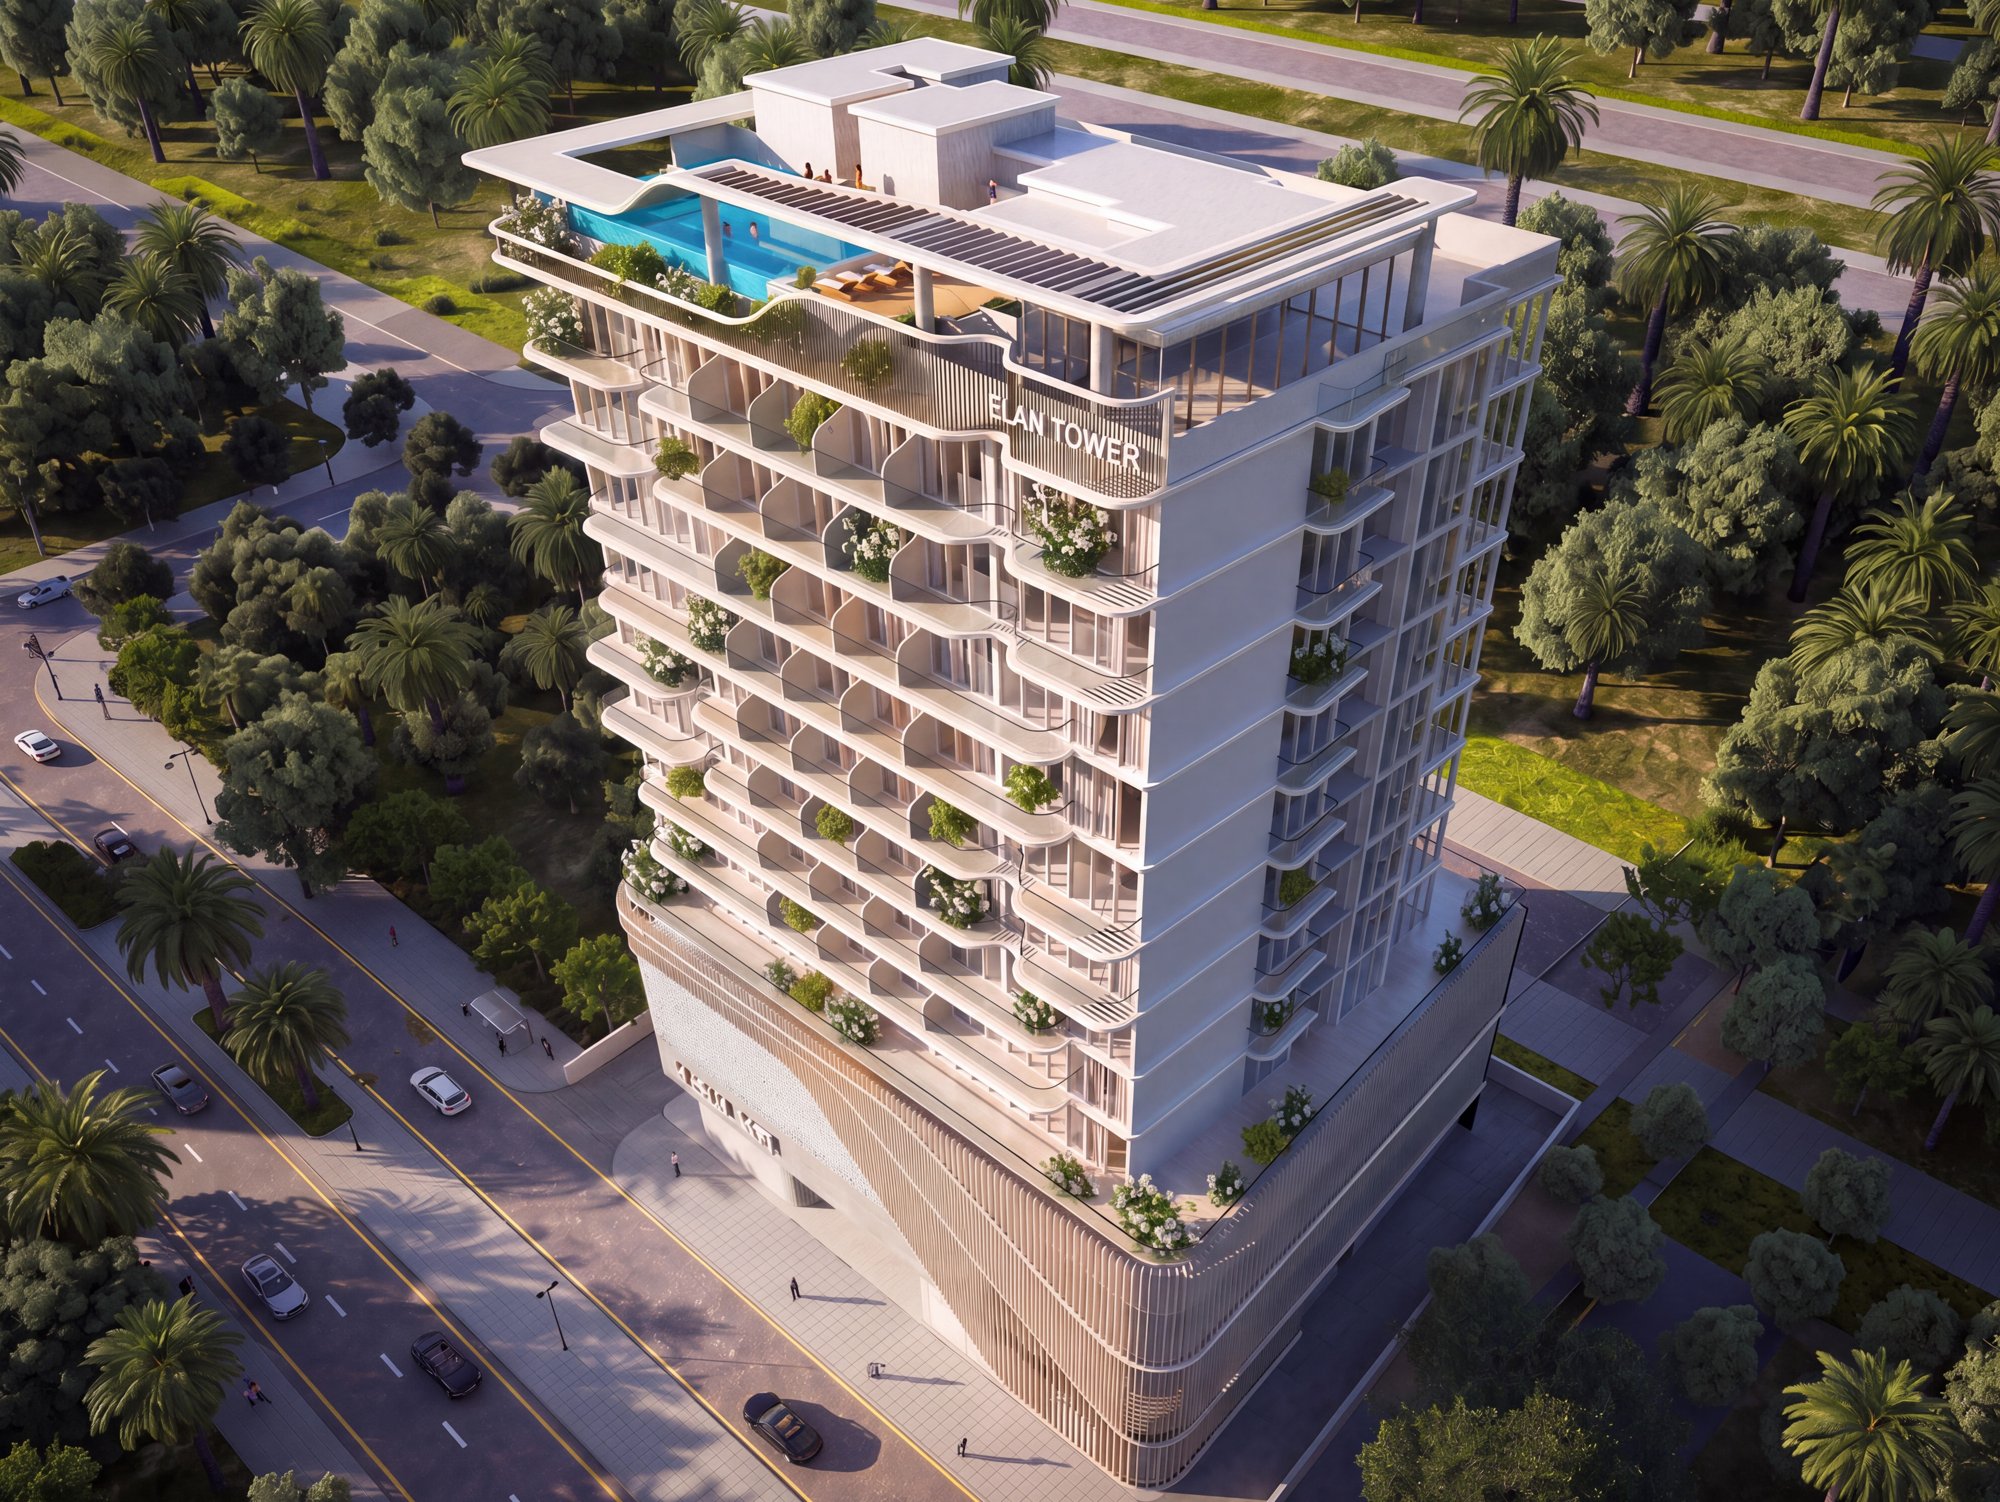
To see what is currently available, our Dubai off-plan listings page lists active developments, including Elan Tower at Alfulaiti Residences in Dubailand, Eltiera Views by Ellington, and Palm Jebel Ali, The Beach and Coral Collection Frond F by Nakheel.
Frequently asked questions
What did the Federal Reserve decide on 16 September 2026?
The Fed raised its target federal funds rate range by a quarter point, to 3.75-4.00%, in a unanimous 12-0 vote. The statement gave no guidance on future moves, so this is a confirmed rate rise with no announced path beyond it.
How did the CBUAE respond to the Fed's move?
The Central Bank of the UAE raised its Base Rate from 3.65% to 3.90%, effective Thursday 17 September 2026, as reported by Gulf News on 16 September 2026. This follows the dirham's peg to the US dollar, which links CBUAE policy to Fed decisions.
What is EIBOR, and why does the date matter?
EIBOR is the Emirates Interbank Offered Rate, the CBUAE's daily benchmark used to price variable-rate loans including mortgages. It changes every day, so any EIBOR figure needs its date attached; the 3-month rate was 3.99% on 1 September 2026, 4.13% on 16 September 2026 and 4.36% on 18 September 2026.
Are Dubai's mortgage loan-to-value limits new?
No. The CBUAE's loan-to-value caps come from Rulebook Article 3, Circular 31/2013, effective 28 December 2013 and still marked in force. Nothing about these caps changed with the September 2026 rate move; they were already in place, and they apply to the same buyer categories as before.
Does a rate hike affect developer instalment plans?
Not directly. Instalments during construction go straight to the developer with no bank loan involved. A handover balance often does need a mortgage later, though, and that loan's rate will be whatever applies on the day it is drawn. That is not known in advance.
Will my mortgage payment go up because of this hike?
It depends on your loan structure. If you are inside a fixed-rate period, nothing changes until that period ends. If you are variable or approaching the end of a fixed period, the effect lands at your bank's next reset point. Ask your lender for your specific date.
Questions about how this affects your own purchase?
We are happy to walk through what these rules mean for a specific property or payment structure you are considering. Speak to us on WhatsApp or book a free 15-minute consultation.
Muhammad Zohaib Saleem — Founder, Early Bird Properties (RERA / DLD ORN 37167). In Dubai real estate since 2013.
No developer marketing fees; recommendations based solely on investor interest alignment. Figures here are dated to their named sources (federalreserve.gov; Central Bank of the UAE EIBOR page and Rulebook; Gulf News, 16 September 2026; Khaleej Times, 17 June 2026, before the hike) and EIBOR changes daily, so confirm the current figure with your lender. This is general information, not legal or financial advice.